

The Finnish city of Kokkola has developed an unusually large concentration of metals processing and battery-related industries. Saku Vuori, the new director general of the Geological Survey of Finland, says the area is significant even by European standards. Plans for an aluminium smelter could strengthen its position further, although no final investment decision has yet been made.
Saku Vuori took office as director general of the Geological Survey of Finland, GTK, in August 2026. During a visit to the agency’s Kokkola office, he highlighted the city’s role in Europe’s industrial value chains.
Vuori was already familiar with Kokkola Industrial Park from his previous position as managing director of Metallinjalostajat, the Finnish association representing the metals refining industry.
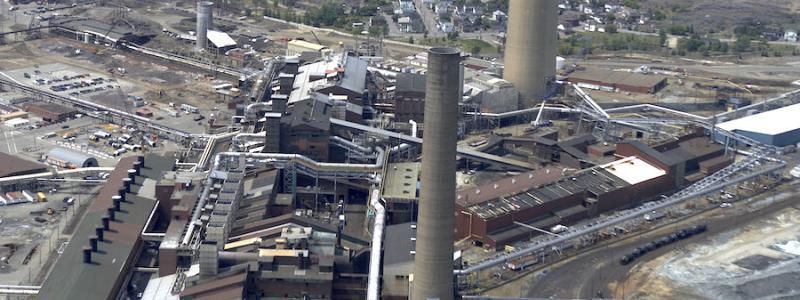
One of the area’s largest operations is Boliden’s zinc smelter. In recent years, however, Kokkola has also emerged as an important centre for battery materials.
– The area is large by European standards and even more significant from a Finnish perspective. Improving the operating conditions for industrial parks of this kind is important, Vuori told Finnish public broadcaster Yle.
Several stages of the metals value chain in one location
Cobalt is processed in Kokkola by Jervois Finland and Umicore. The metal is used in certain types of lithium-ion batteries, as well as in superalloys and hard metals. The city’s substantial processing capacity makes Finland an important European producer of refined cobalt products.
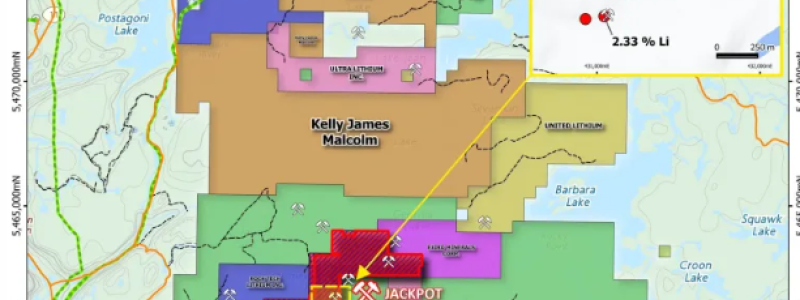
The Keliber lithium project in Central Ostrobothnia could also become strategically important. Mining at the Syväjärvi open pit began in February 2026, while the concentrator at Kaustinen has been completed. A lithium refinery has been built in Kokkola with the capacity to produce around 15,000 tonnes of lithium hydroxide annually.
Full-scale operation of the entire production chain has not yet been established. Project owner Sibanye-Stillwater has linked the next stages of commissioning partly to market conditions and discussions over European support measures for domestic lithium production.
Lithium hydroxide is used to manufacture cathode materials for electric vehicle batteries. If the entire Keliber production chain enters operation, Finland will have an integrated supply chain extending from mining and concentration to the production of a refined battery chemical.
Another advantage is the concentration of several industrial companies within the same area. Raw materials, by-products, energy and infrastructure can be shared or transferred between plants. This can reduce transport requirements and make it easier to recover waste heat and secondary material streams.
– Circular solutions are considerably easier to implement in an integrated industrial park than when plants are scattered along the coast, Vuori said.
Aluminium smelter remains at the planning stage
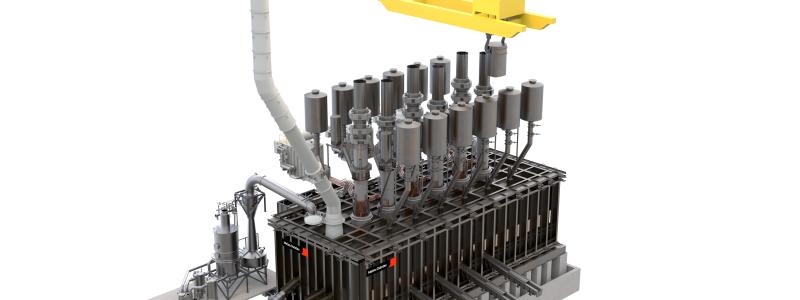
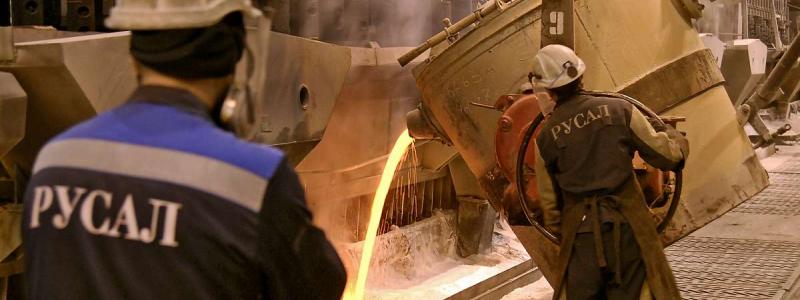
One of the region’s largest potential investments is Arctial’s proposed aluminium smelter in Kokkola and neighbouring Kruunupyy. The company is conducting a feasibility study with several industrial and financial partners.
Arctial intends to produce primary aluminium with a lower carbon footprint than the global industry average. Primary aluminium is produced from alumina and differs from recycled aluminium, which is made by remelting metal scrap.
The project remains at the planning stage. A pre-feasibility study was completed in May 2026, while a final investment decision is expected no earlier than 2026–2027. Financing, energy supplies, permits and the plant’s technical design must still be secured.
Vuori nevertheless considers the selection of Kokkola as a prospective location an achievement for the region.
– The fact that the company is examining the possibility of investing here is already significant. I strongly hope that the project is completed and Finland gains domestic aluminium production, he said.
If built, the facility would, according to Arctial, be the first new primary aluminium smelter in continental Europe for more than 30 years. This remains the company’s stated ambition rather than an approved investment.
GTK maps resources concealed beneath the surface
The EU wants to reduce its dependence on imported critical raw materials, particularly in markets where extraction or processing is dominated by a small number of countries. Member states are therefore expected to develop national exploration programmes and improve their knowledge of geological resources.
The schist belts of Finland’s Ostrobothnian regions are among GTK’s priority research areas. Despite extensive exploration following the discovery of Keliber’s lithium deposits, the agency says substantial areas remain insufficiently investigated.
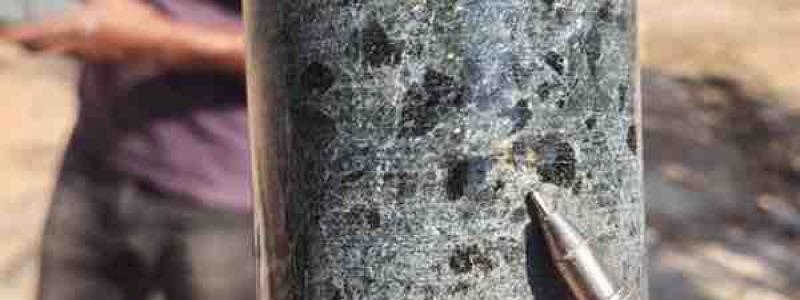
Around 97 per cent of Finland’s bedrock is covered by soil, forests, wetlands or peatlands. Potential mineral deposits can therefore rarely be identified directly at the surface. Geological investigations require methods including geophysical surveys, sampling and drilling.
GTK’s primary role is not to discover commercially viable mines. The agency studies the geological processes that may have created mineral deposits and produces regional data that companies can use in their own exploration programmes.
Central Ostrobothnia also contains occurrences of beryllium and titanium, both included in the EU’s lists of critical or strategic raw materials. The known beryllium concentrations have not been considered high enough for commercially viable extraction. The possibility of developing a titanium mine in the region is being reassessed, but important technical and economic questions remain unresolved.
GTK also operates a pilot mineral-processing plant in Outokumpu. Ore samples can be treated there on a larger scale to test concentration methods and generate technical data for possible investment decisions.
Kokkola’s future position will consequently depend on more than the metals found beneath the ground. Access to competitively priced energy, reliable infrastructure, financing and European customers willing to purchase the refined products will be equally important.
Sources: Yle, Geological Survey of Finland, Arctial, Sibanye-Stillwater and Finnish Minerals Group.